
The NQ 5-minute opening range breakout is one of the simplest intraday setups to describe and one of the hardest to trade consistently by hand. The idea fits in a sentence: mark the high and low of the first five minutes after the 9:30 AM ET cash open, then trade a move that breaks out of that range. This guide covers what the range is, how a breakout is usually defined on Nasdaq-100 futures, why fakeouts happen, the filters traders use to avoid them, and how position size changes between NQ and MNQ.
What is the 5-minute opening range?
Nasdaq-100 futures trade nearly around the clock on CME Globex, but the US cash equity session opens at 9:30 AM ET. That open is when stock orders that built up overnight meet the market, and the first minutes of the session are often among the most active of the day.
The opening range is simply the highest high and lowest low printed in a fixed window after that open. In a 5-minute opening range, the window runs from 9:30:00 to 9:35:00 AM ET. On a 5-minute chart it is the first bar of the session; on a 1-minute chart it is the first five bars, which shows how price got there.
Two practical points matter more than they seem:
- Time zone. The range is defined in Eastern Time. If your platform or computer runs on another time zone, convert it, or the “first five minutes” will be the wrong five minutes, especially in the weeks when the US and Europe change clocks on different dates.
- Session template. The range is taken from the cash open, not from the start of the Globex session the evening before. Make sure the chart’s trading hours match what you think you are measuring.
How does an opening range breakout work on NQ?
Once the range is set at 9:35, an opening range breakout (ORB) strategy waits for price to leave it. A long signal is a move above the range high; a short signal is a move below the range low. From there, rule sets differ on three questions:
- What counts as a break? A single tick through the level, or a bar that closes beyond it. Waiting for a close filters some false moves but gives a later, often worse, entry.
- How do you enter? A stop order at the level, a market order on the signal, or a limit order that waits for price to come back. Each trades off fill certainty against entry price.
- When does the window close? Many traders only accept signals for a limited time after the open, on the idea that the opening move loses its edge as the morning goes on.
The exit side needs the same precision: a profit target, a protective stop or exit, and a rule for what happens if neither is hit before you stop trading for the day.
Why do opening range breakouts fake out?
The first minutes after the open are where NQ is most likely to whipsaw: price pokes through the range high, reverses, breaks the low, and reverses again. A few reasons this happens:
- Opening order flow is lopsided. Orders that queued overnight hit the market at once, and the first move can reflect that imbalance rather than a direction that lasts.
- Obvious levels attract orders. The range high and low are visible to everyone watching the open, so stops and breakout entries cluster just beyond them. Price can run those orders and then turn.
- Narrow ranges break easily. When the first five minutes are quiet, the range is small and almost any move breaks it. A break of a very tight range says little.
- Scheduled news. Data released before or during the morning session can push price through a level and back within a minute or two.
No filter removes fakeouts. The aim of the filters below is to skip the breaks that are most likely to be noise, accepting that some good trades will be skipped too.
Filters traders use on the NQ opening range
Volatility (ATR)
Average True Range (ATR) measures how far price typically moves per bar. Traders use it two ways around the open. First, to judge the range itself: a range that is tiny relative to recent ATR is prone to random breaks, while a range that is huge may already contain the day’s move. Second, to skip signals when recent bars are unusually wide, because a stop of a given size is much easier to hit when every bar is large. Test any threshold on your own data.
Breakout bar quality (body as a share of range)
A bar that closes beyond the level with a large body and a small wick against the trade direction shows price was accepted outside the range. A bar with a long wick back into the range shows the opposite: price went through and was pushed back. A common filter is to require the signal bar’s body to be at least a set percentage of its high-to-low range, and to close near its extreme.
News days (CPI, jobs, FOMC)
Scheduled economic releases change how the open trades. The US Consumer Price Index and the employment report are released by the Bureau of Labor Statistics at 8:30 AM ET, before the cash open, so the opening range on those days often forms in the aftermath of a large move. FOMC decisions are published in the afternoon, but the days around them can trade differently. Check the BLS CPI release schedule, the employment situation schedule and the Federal Reserve FOMC calendar before each week. Many ORB traders sit out high-impact days; either way, decide in advance.
Risk and position sizing: NQ vs MNQ
Position size on Nasdaq-100 futures comes down to contract math. According to CME Group’s contract specifications, the E-mini Nasdaq-100 (NQ) is $20 × the Nasdaq-100 Index and the Micro E-mini Nasdaq-100 (MNQ) is $2 × the index. Both have a minimum tick of 0.25 index points.
- NQ: $20 per point, $5.00 per tick, per contract.
- MNQ: $2 per point, $0.50 per tick, per contract.
So a stop 20 points from entry risks $400 per NQ contract and $40 per MNQ contract, before commissions and slippage. Ten MNQ contracts carry the same point value as one NQ contract.
A simple way to size: decide the most you are willing to lose on one trade, divide by the stop distance in points times the dollar value per point, and round down. Micros make this practical on smaller accounts, because they let you size in steps one tenth as large. Two cautions apply. Commissions and fees are charged per contract, so costs take a larger share of each trade on micros. And a market exit in a fast open can fill worse than the stop price, so the real loss can be larger than the plan. For prop firm accounts, check how the firm measures drawdown and whether it allows automated strategies before you size anything.
How automation helps in NinjaTrader 8
The 5-minute opening range breakout is unforgiving to trade by hand. The range has to be measured at exactly the right time, the signal has to be judged against several filters within seconds, the order has to go in at once, and the hardest part, sitting out a day or stopping after a loss, has to happen when the market is moving fastest. These are all things a strategy does the same way every time.
In NinjaTrader 8, an automated strategy runs on a chart, reads each bar as it closes and places orders through your own broker or prop firm connection. The range is always taken from the same window, filters are applied without second-guessing, and daily limits are enforced. It also brings responsibilities. The platform must stay running and connected while a trade is open, a strategy can only follow the rules it was given, and automation does not make a setup profitable. Regulators warn about trading systems sold with exaggerated claims; the CFTC’s advisory on trading system fraud is worth reading before you buy any automated strategy, including ours.
How Sovren approaches the NQ opening range
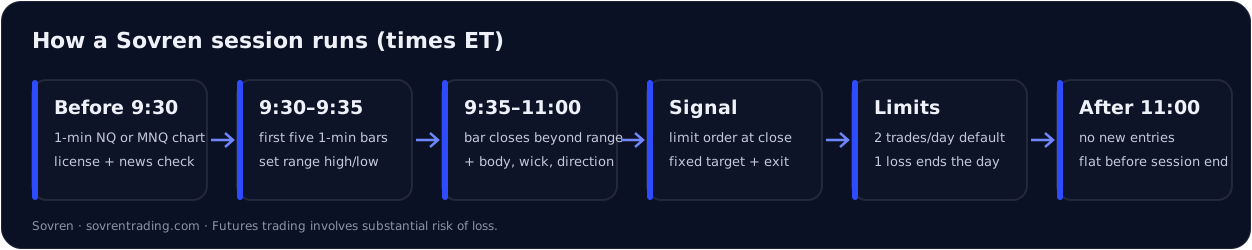
Sovren is an automated strategy for NinjaTrader 8 built around this setup. It takes the 9:30–9:35 AM ET range from 1-minute NQ or MNQ bars, accepts signals until 11:00 AM ET, requires a bar to close beyond the range and pass body, wick and direction checks, skips signals when recent ranges are unusually wide, sits out scheduled high-impact news days by default, and ends the day after one losing trade. The full rule set is on how Sovren trades the opening range breakout, and running it on micros is covered on the MNQ page.
Sovren’s live trading record is published on the results page. Past performance is not indicative of future results, and your results will differ.
Key takeaways
- The 5-minute opening range is the high and low from 9:30 to 9:35 AM ET; get the time zone and session template right first.
- Define the break, the entry, the exit and the signal window before the open.
- Expect fakeouts. Volatility, bar-quality and news filters reduce them but never remove them.
- Size from the stop distance and the contract’s dollar value per point: $20 for NQ, $2 for MNQ.
- Automation enforces the rules consistently; it does not guarantee results.
Risk disclosure. This article is general education, not investment advice or a recommendation to trade. Futures trading involves substantial risk of loss and is not suitable for every investor. Past performance is not indicative of future results. Read the full disclosures.